
In prior commentaries, we have highlighted Morningstar’s global research uncovering investment opportunities in unpopular and overlooked regions and sectors such as South Korea and US Healthcare. To date, the allocation to South Korea has delivered meaningful returns, while the market has yet to fully recognise the opportunity presented by current valuations in the US Healthcare sector.
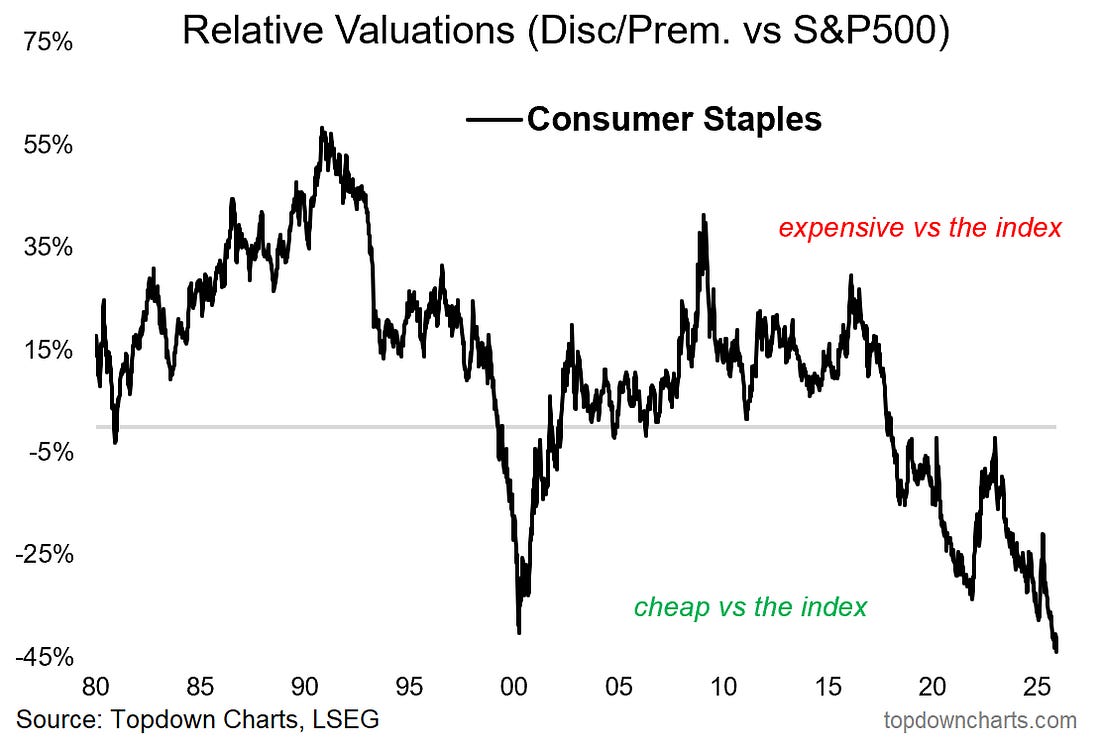
Morningstar has also identified additional opportunities, one of which is US Consumer Staples. The sector is currently trading at a record relative valuation discount to the S&P 500; close to 45%, or approximately half the valuation of the broader US equity market. One could argue that this is justified, given the perceived upside of growth stocks relative to more defensive sectors, or point to concerns that developments such as GLP-1 weight-loss drugs (e.g. Ozempic) may weigh on food demand within the staples sector. However, regardless of the prevailing narrative, the extent of this valuation gap is extreme.
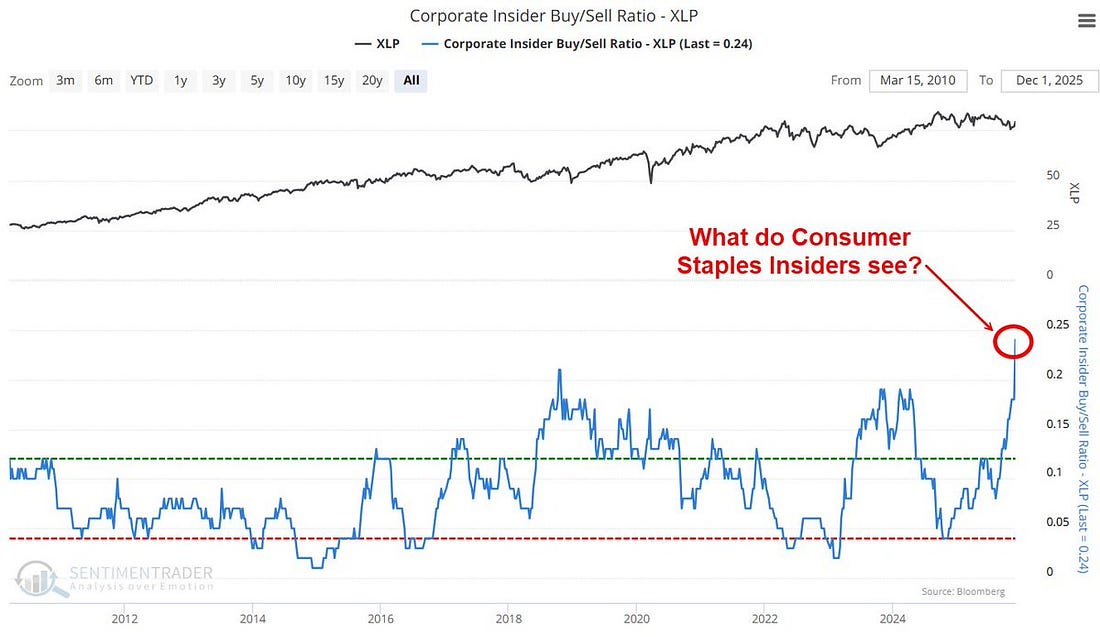
Importantly, Morningstar is not alone in identifying this value. Corporate insiders; those with direct insight into their businesses, are purchasing shares of their own companies at record levels. There is particularly strong insider buying within the Consumer Staples sector. This is a segment of the equity market that has been largely left behind, with Consumer Staples broadly flat year-to-date, compared to gains of more than 20% for the Nasdaq 100.
Currently, the funds have approximately 8% exposure to Consumer Staples. When combined with allocations to other traditionally defensive sectors, such as Healthcare and Utilities, total exposure to defensive sectors represents approximately one quarter of each fund’s equity allocation.
This positioning enhances the overall robustness of the portfolios while simultaneously taking advantage of attractive valuation opportunities.